
Your Local Mortgage Lender
Located in Mesa, Arizona
Personalized Mortgage Experience
Brian Barker offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Mesa, Arizona.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
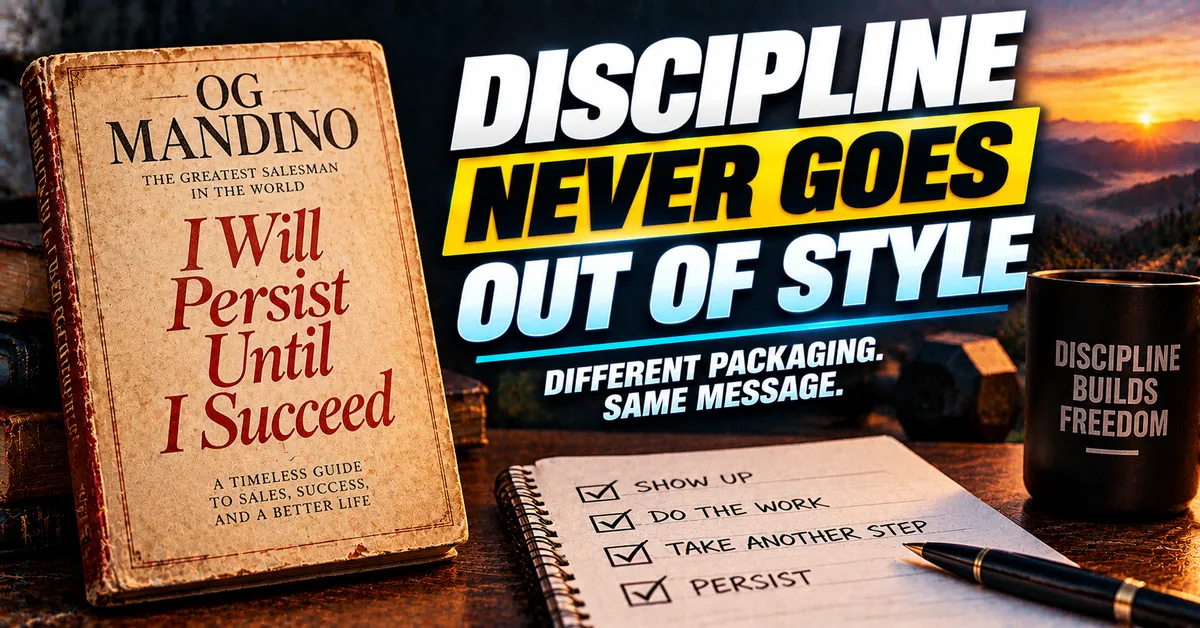
Before the Gurus and the Cold Plunges There Was OG Mandino and the Message Has Never Changed
The Original Before Anyone Knew What an Original Was
Before Gary Vee. Before Alex Hormozi. Before Mark Wahlberg was anyone other than Marky Mark. Before Instagram turned discipline into a content category and cold plunges became a personality. Before the Lamborghini thumbnails and the six-figure course launches and the blue checkmarks that signal you have arrived.
There was OG Mandino.
Who OG Mandino Was and Why It Matters
Og Mandino wrote one of the greatest sales books ever written and he did it in 1968. John F. Kennedy had been gone for five years. Camelot was still a cultural memory rather than a historical footnote. There was no podcast to promote it. No social media algorithm to amplify it. No personal brand to build around it. Just the work and the words.
The most enduring line from that book is a simple declaration. I will persist until I succeed.
No Lambo. No six a.m. cold plunge. No manufactured urgency. Just a commitment to showing up and taking another step and then another step until the thing gets done.
Why the Packaging Changes and the Message Stays the Same
Brian Barker makes the observation that history repeats itself in this particular way. Every generation discovers the same truths about discipline and consistency and repackages them with the aesthetics of its own moment. The gurus of today are teaching the same principles Mandino was writing about fifty-plus years ago. The content category is new. The message is not.
That is worth sitting with on October first as the winter arc conversation begins across every platform simultaneously. Everyone deciding today is the day. New routine. New identity. New version of the same commitment that every motivated person makes at predictable intervals throughout the year.
The ones who actually change something are not the ones who had the best content strategy for announcing the change. They are the ones who showed up again the next day and the day after that without needing an audience for it.
What This Applies To
Brian extends this to his home buyers directly. The path to homeownership for most people is not a single dramatic decision. It is a series of unglamorous steps taken consistently over time. Building the credit. Saving the down payment. Having the financial conversations that feel uncomfortable. Working with a lender who treats the process with the seriousness it deserves rather than the hype it does not need.
Show up. Do the work. Take another step and then another step.
That was true in 1968. It is true today. And it will be true long after the current generation of gurus has been replaced by the next one.
Reach out to Brian Barker to start the conversation about your path to homeownership. No hype. Just the work.
Sources
NAR.realtor
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com
NationalFoundationForCreditCounseling.org

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

